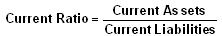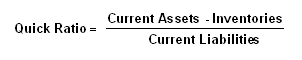Showing posts with label Current Ratio. Show all posts

Friday, March 11, 2016

Fundamental Analysis: Solvency ratios and Liquidity ratios

Selecting a company for investing is not a trivial task. Many small investors get into trouble because they buy a stock without doing adequate homework. 

A stock may be in the news as a potential multibagger, or may be approaching its 25th or 50th year of existence or has a reputation of distributing large dividends.

Those may be good reasons for someone to buy the stock in the hope of making some quick gains. But for building wealth for the long-term, more detailed analysis is necessary to determine a company's staying power.

Ratio analysis is a good way to differentiate a company from its peers and competitors. But there are so many ratios to analyse - where should you start?

The state of financial health of a company is one of the first things you should evaluate. If the financial foundation is strong, many other shortcomings can be overridden.

Solvency ratios - like debt/equity and interest coverage - indicate the ability of a company to meet its long-term financial commitments.

Liquidity ratios - like current ratio and quick ratio - indicate how well a company can meet its short-term financial obligations.

To learn more about solvency and liquidity ratios - how to calculate and evaluate them - visit the following links at investopedia.com:

Link 1

Link 2

Sunday, April 24, 2011

How to identify winning stocks – a guest post

The Sensex and Nifty have been quite volatile lately, jumping up and down like a kid on a trampoline. Small investors are not sure whether to buy or sell. At times like these, it may be better to sit back and do nothing.

Niteen has a better idea. Learn how to identify winning stocks using his 12 parameters. If you like his post, please write a comment or query. Your feedback may motivate him to contribute regularly.

-------------------------------------------------------------------------------------------------------------

After 18 years in the stock market, I have observed that most small investors are only interested in tips for making quick money. But without exception, they end up losing money. Remember that the reverse of ‘TIP’ is ‘PIT’. ‘TIP’s can take you to the ‘PIT’s. There are no short cuts to making money. The stock market is a place that requires a highly disciplined approach. To make money, investing should be viewed as a long term process.

How to identify a winning stock without depending on tips? What are the parameters that help in choosing a winner?

The most important parameter is the ‘Margin of Safety’. The concept of margin of safety was first introduced by Benjamin Graham, author of investment classics like ‘The Intelligent Investor’ and ‘Security Analysis’.

Graham said: "Margin of Safety is always dependent on the price paid". One should buy a stock when it is worth more than its market price. This is the central thesis of the value investing philosophy, which emphasises preservation of capital. Graham looked at unpopular or neglected companies with low P/E and P/BV ratios.

If you feel that a stock is worth Rs 100, buying it at Rs 75 will give you a margin of safety. In case your analysis is incorrect and the stock is worth only Rs 90, the Margin of Safety provides a cushion against a possible loss. In India, markets tend to be volatile, so it becomes more important to look at each stock through the magnifying glass of Margin of Safety.

Very few stocks make it through the stringent screening process given below, and many potentially investment-worthy stocks can get excluded. If you come across any tips and get tempted to invest, at least you should screen those stocks through these parameters to ensure that you are not overpaying.

There are 12 parameters grouped under four heads.

(I)  Valuation & returns

  • P/E ratio < 40% of highest average P/E ratio over previous 5 years: take the highest P/E ratio of each year for last 5 years and then take an average
  • Earnings yield (E/P) > 2 x (RBI bond yield): RBI Bonds give a return of around 8%
  • Dividend yield > 2/3 x (RBI bond yield): Dividend yield is calculated by dividing the last dividend paid by a company, by the current stock price. Some companies retain earnings and do not pay dividends to maintain growth. But most blue-chip companies that have grown from the time they were not blue-chip, have consistently paid dividends for many years

(II)  Balance Sheet related

  • Current ratio > 2.0. This will give you a positive Net Current Asset Value (NCAV) number per share
  • Stock price < 1.2 x (Book Value)
  • Inventory trend: Inventory trend should reflect revenue numbers. Goods are produced to be sold, and not stored in a warehouse. If inventories increase faster than sales, a problem is brewing
  • Minimum 12% Return on Invested Capital (ROIC)
  • Debt/Profit =<5 and Debt/Equity ratio =<1.5: A company should pay its debt out of its profits, and not out of the equity base of the company. A ratio of 5 means that the debt can be paid out of 5 years profits

(III) Profit & Loss related

  • Revenue and profit should preferably increase consistently during last 5 years. A drop in any one of the 5 years can be considered also
  • Consistently paying dividends, bonuses: This is in line with (I) above

(IV) Governance

  • Published Statements of previous 6 months/Management Discussion and Analysis (from Annual Report): If the management is over optimistic about future earnings, an investor should stay away. Infosys, which is well-known for its transparency, has always been cautious in projecting future earnings
  • Shareholding pattern – Buying, selling or pledging: If management is selling/pledging their holdings, the stock should be avoided

The above parameters are available (or, can be calculated) free of cost from sites like: www.icicidirect.com, www.anagram.co.in or from economictimes.indiatimes.com.

There can be cases where you need to consider some additional parameters. The measurement of one parameter can be relaxed due to the strength of another parameter. This comes through experience and a new investor/analyst should avoid relaxing the parameters.

-------------------------------------------------------------------------------------------------------------

(Niteen S Dharmawat is an MBA who has been working with Indian IT companies. A firm believer in long-term financial planning, and an 18 years veteran of the stock market, he likes to analyse the economy, and individual stocks. He also conducts investor education sessions.

Niteen blogs at http://dharmawat.blogspot.com.)

Related Post

What exactly is the Margin of Safety?

Thursday, November 5, 2009

What does the Interest Coverage Ratio signify?

The Interest Coverage ratio (also called Times Interest Earned) is another measure of a company's financial health. It signifies the ability of a company to meet its debt obligation.

In earlier posts, I have covered Current Ratio, Quick Ratio and Debt/Equity ratio. These financial ratios, together with cash flows from operations give a clear view of the financial soundness of a company.

The definition of the Interest Coverage Ratio is simple enough. It is the EBIT divided by interest expense:

Interest Coverage Ratio

EBIT is the earnings (or Profits) before interest and tax payments. It is calculated by adding the interest expense to the PBT (Profits Before Tax). The PBT and interest figures can be obtained from the Profit and Loss statement in any Annual Report of a company.

Let us look at Maharashtra Seamless' Mar '09 annual figures. PBT was 385 Cr; interest expense was 11.6 Cr. That gives an EBIT of (385+11.6=) 396.6 Cr. The interest coverage ratio is 34.

What does that mean? Maharashtra Seamless can pay its debt obligation 34 times with its earnings before interest and taxes. Let us look at another company - 3i Infotech, which is quite popular with small investors.

PBT was 288.5 Cr; interest expense was 95 Cr for year-ending Mar '09. EBIT = 383.5 Cr, not much lower than that of Maharashtra Seamless. But the difference in the interest coverage ratio is startling - an adequate 4, against a very comfortable 34!

An interest coverage ratio of less than 1.5 means that the company may have trouble meeting its debt obligations and may need to borrow more to pay its previous debts. A ratio less than 2.5 should be treated as a warning sign. Avoid companies with a ratio less than 1.

It is important to check a company's financial health over the past 5 years or more. A decreasing interest coverage ratio - even if it is above the threshold values mentioned - is a red flag. Look for companies with consistency of earnings. They can afford to have a lower interest coverage ratio - though the higher the ratio, the better their financial health.

Conservative investors can use a more stringent ratio, by using only EBI on the numerator. That is, they should deduct the tax amount from EBIT before calculating the Interest Coverage Ratio.

This concludes the series of posts on how to evaluate the financial health of a company. Readers may want to go through an exercise of calculating the financial soundness of stocks in their portfolios. The time spent will be well worth it.

Thursday, October 15, 2009

About Current Ratio and Quick Ratio

In-depth interpretation and analysis of financial ratios are best left to CAs and CFAs. For ordinary small investors, understanding the concepts behind the Current Ratio and the Quick Ratio enables a reasonable assessment of the financial health of a company.

If you are the kind of investor who only looks at the Profit and Loss statement in an Annual Report to check the Net Profit and Dividend amounts before tossing it in the dustbin, then you need to make a little more effort to become a better investor.

Look at the Cash Flow statement to check that the Cash Flow from Operating activities is positive. Then, calculate the Current and Quick ratios.

Current Ratio

This ratio is obtained by dividing the Current Assets figure in the Balance Sheet by the Current Liabilities. A good ratio is between 1.5 and 2. A ratio of 1.0 or less may mean that the company may face difficulty in meeting its short-term debt obligations. A ratio of 3 or more may not necessarily be better, as explained below.

Current Ratio

The range of Current Ratios are different for different industries and sectors. So, comparing the ratio with the company's competitors will give a better idea of industry norms and the company's position.

Current Assets typically comprise: inventories, cash and cash equivalents, accounts receivables (debtors), loans and advances.

Current Liabilities include: interest payments, accounts payables (creditors), provisions for payments of taxes, dividends, retirement and other benefits.

The Current Ratio indicates whether the company will be able to meet its payment obligations that become due within the year. It can do this by using the cash, or by collecting payments from its debtors, or by quickly turning over inventory to generate cash.

Too high a Current Ratio could mean:

(a) too much inventory - which may not be good because it may be valued at a cost which can't be realised later; this is particularly true of the retail industry, where inventories often need to be marked down for discount sales due to spoilage or change in fashion

(b) poor debt collection, or inadequate credit facilities from suppliers -indicating management inefficiency or a poor business model.

Quick Ratio

Due to concerns mentioned above, the Quick Ratio is often used as a better test of a company's liquidity position. That is why it is some times called a Liquidity Ratio or Acid Test Ratio.

The Quick Ratio is obtained by subtracting inventories from the Current Assets figure, before dividing by the Current Liabilities.

Quick Ratio

A ratio of 1.0 is considered good enough. It can be higher for certain industries, but too high a ratio may indicate management inefficiency.

What is the reason for subtracting inventories? The first reason has been mentioned already - the cost of inventories in the Balance Sheet may not reflect the real value. The second, and more important reason is that it may not be easy for a company to turn inventory into cash fast enough to meet payment obligations.